
OLED-Info Pro continues to deliver in-depth, tightly focused research and commentary on the display ecosystem, blending technology analysis, market structure, and strategic outlooks. The latest batch of eleven premium articles covers an unusually wide span, from the physics of chiral emitters and the transistors hiding behind every pixel, to Korean strategy, Chinese industrial policy and the macro forces now bending OLED demand.
This batch also introduces two new series: Bright Side with Brannan, a science column by Prof. Alexander Brannan of the University of Manchester, and a seven-part practical guide to OLED display backplanes. Below is an overview of the latest premium stories, and why each is worth your time.
The second article in Prof. Alexander Brannan's column asks a simple question that the research literature often skips: what does circular polarization actually buy an OLED display? It explains what circularly polarized luminescence (CPL) is, and points out that circular polarization is already inside most commercial OLED panels - a linear polarizer plus a quarter-wave plate, used to kill ambient reflections. The catch is that the same stack absorbs more than half of the panel's own emission.
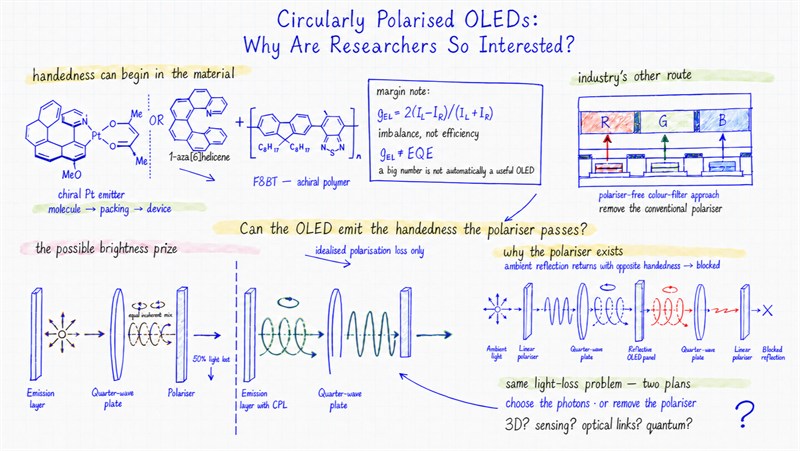
The article then walks through the three routes researchers use to generate CPL directly - the chiral emitter itself, chirality built into the emitting layer, and the surrounding optical device - plus a possible fourth route through spin injection. Crucially, it explains how to read the dissymmetry factor gEL, so you can tell a genuinely useful result from a headline number that would improve transmitted brightness by 0.005%. It closes with the industry's own answer to the polarizer problem - Samsung's Eco2OLED and LEAD, BOE's COE, Tianma's CFOT - and a perspective from Prof. Matthew Fuchter.
Karl Guttag: why transparent microdisplays are impractical for AR glasses (August 10, 2026)
A guest article by Karl Guttag of KGOnTech, a display industry veteran and one of the leading independent analysts of AR and VR display technology, answering a question we are asked often: why not simply place a transparent OLED or microLED panel in front of the eye and be done with it? Karl's answer starts from a principle worth remembering - the most important measure of an AR display is how it behaves when the display is off.
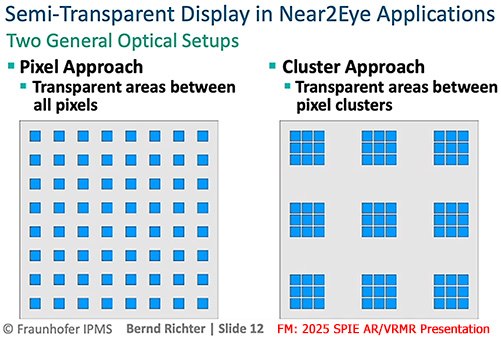
The article works through the full checklist for optical see-through AR: darkening, distortion and diffraction of the real world, rainbow capture, uniformity and contrast of the virtual image, efficiency in watts-per-nit, forward projection ("eye glow") and the social cost that comes with it, and finally cost, weight and size. The fundamental problem is that a large transparent display does not scale down to near-eye use - the pixel-pitch-to-pixel-size ratio is far less favorable, and optics must sit between the pixels and the eye. Fraunhofer IPMS's pixel and cluster approaches for semi-transparent micro-OLEDs are examined as the state of the art.
On-device AI models on flagship hardware have grown from roughly 100M parameters in 2020 to 3-7B today, with 13-20B expected on premium devices by 2028 - and each doubling roughly doubles compute and memory-bandwidth demand. NPUs are far more efficient than running the same workload on a CPU or GPU, but they still draw serious power. This article asks who ends up paying that power bill, and argues that a large part of the answer is the display.
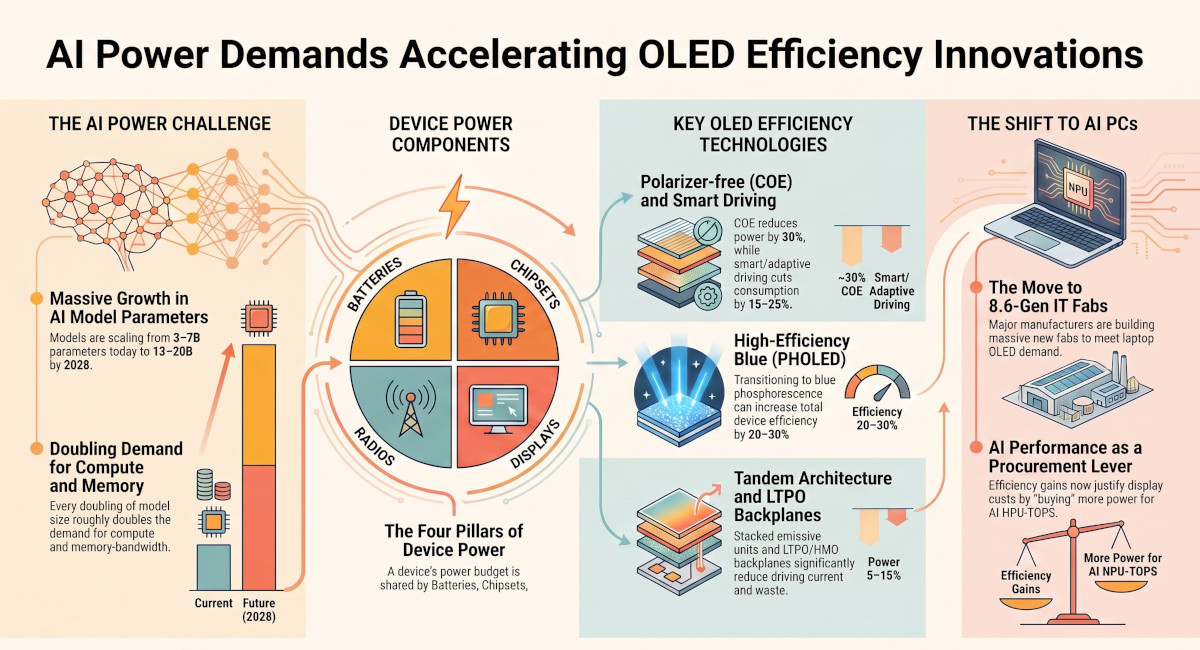
The report breaks device power into its four main consumers - battery, chipset, radio and display - and shows how little headroom the first three have left. Silicon-carbon anodes and solid-state cells are coming, but as step changes rather than overnight leaps; process nodes such as TSMC's N2 deliver real but bounded gains; radio efficiency improves slowly. That leaves the display, and the article maps the next-generation OLED technologies that could take up the slack, with the laptop segment as the place the pressure will land first.
OLED display backplanes, part 2 of 7: amorphous silicon (a-Si) (July 29, 2026)
The second part of our backplane series covers the technology that made the flat-panel era possible. a-Si TFTs are deposited by plasma-enhanced CVD at low temperature in a process that is mature, inexpensive and extraordinarily uniform across the largest sheets of glass in the industry - which is why a-Si scales effortlessly to 10.5-Gen and still dominates low-cost LCD.
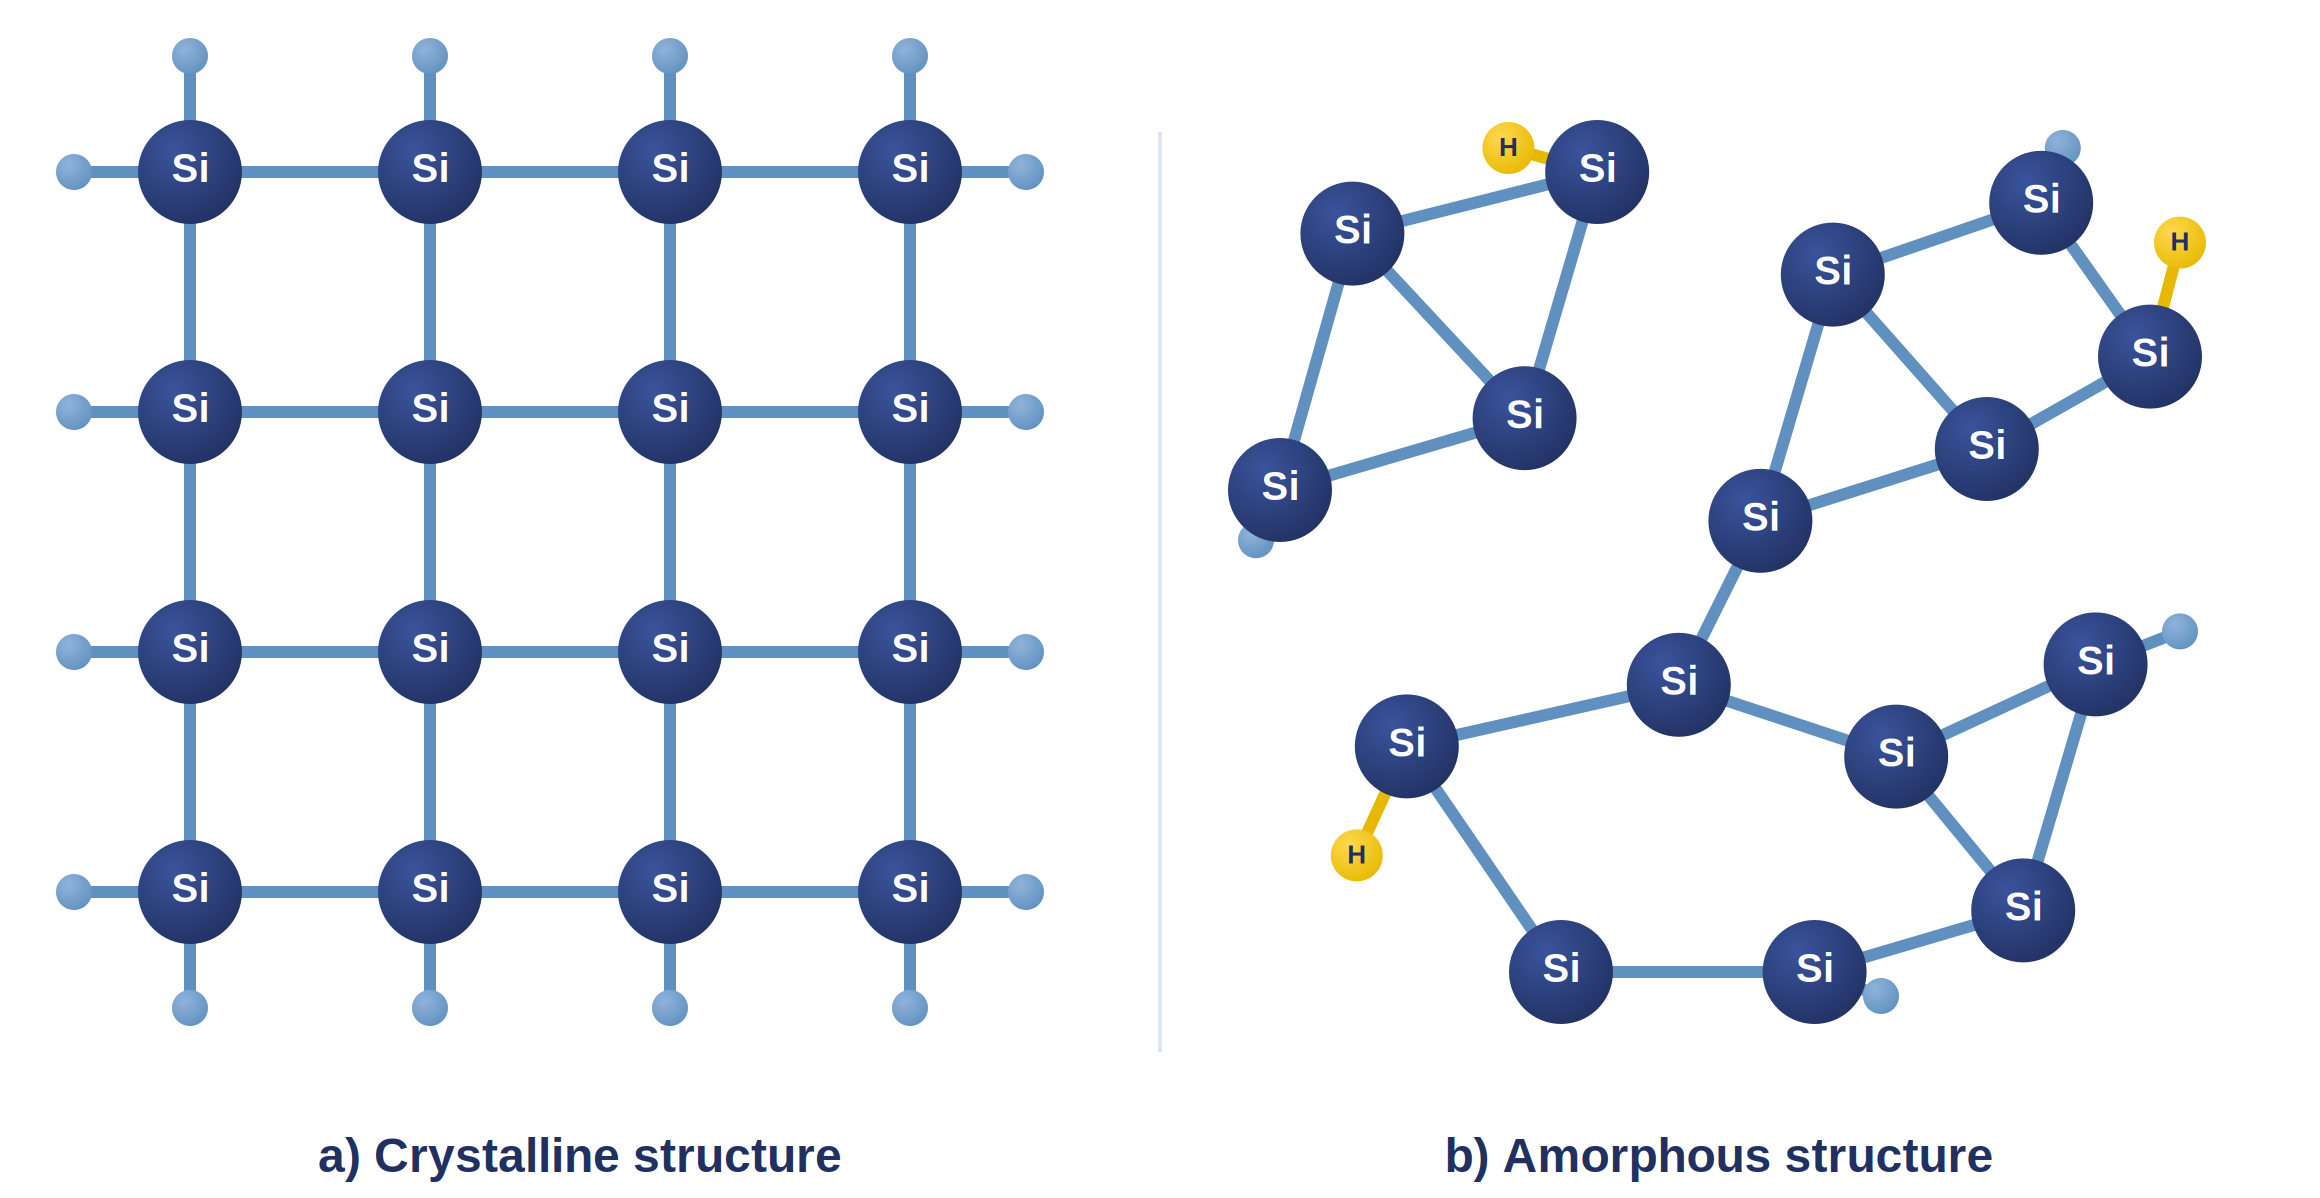
The article explains why a-Si is an excellent fit for LCD, where the transistor only has to act as a switch - charging the pixel's liquid-crystal capacitor once per frame and then sitting idle - and why an emissive OLED pixel is a completely different problem. With an electron mobility of roughly 0.5 to 1 cm²/V·s, about a hundred times lower than the LTPS covered in the next part, a-Si is one of two reasons the technology never reached OLED mass production. We also revisit the early large-size a-Si OLED prototypes, including Samsung's 2005 40-inch panel.
Something interesting is happening in Korea. Over the past few months almost every significant move by Samsung Display and LG Display has pointed in the same direction - upwards, towards the high end, and away from the volume tier of the OLED market. This article asks whether that is now a deliberate strategy: conceding the cheap high-volume OLED business to China, and betting both companies on premium panels for monitors, laptops, tablets and automotive.
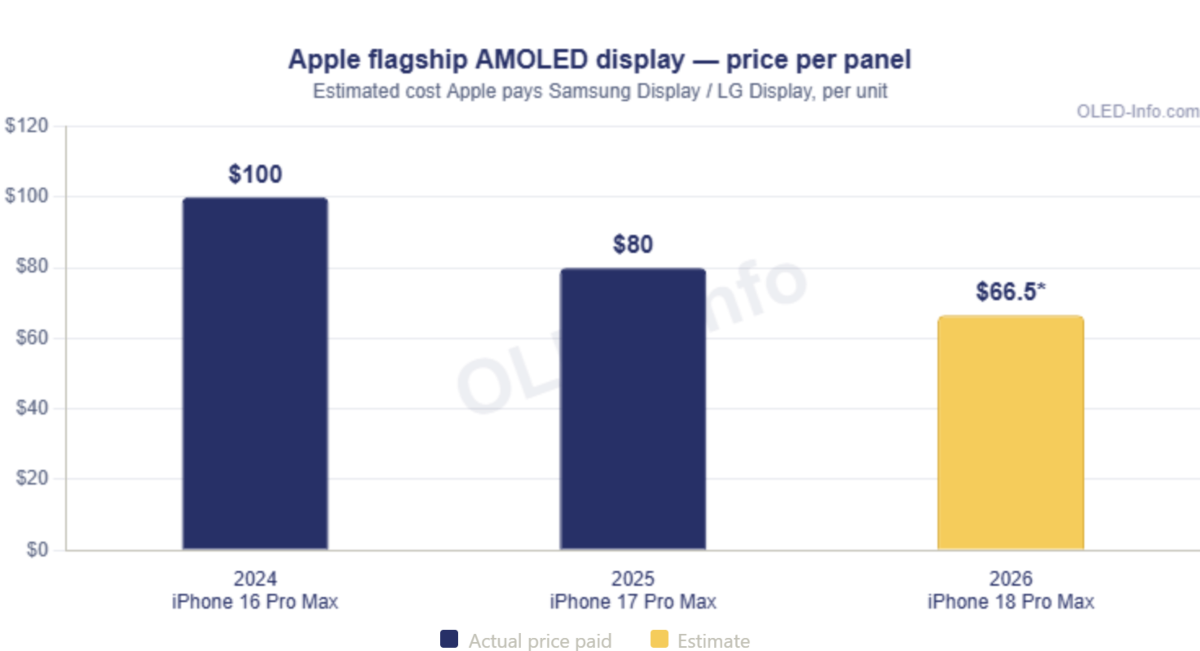
The clearest signal is the 2026 Apple slate - the iPhone 18 series, Watch Series 12, the first foldable iPhone, the OLED iPad Mini and the OLED MacBook Pro - supplied exclusively by Samsung Display and LG Display after BOE failed once again to qualify. But look at the price: Apple is pressuring both suppliers for a 20% cut on the iPhone 18 Pro and Pro Max panels, with a better stack than the year before. The article decodes the other signals, weighs the potential against the risk, and looks at what the strategy means for materials makers, equipment vendors and the rest of the OLED supply chain.
OLED display backplanes, part 1 of 7: introduction & PMOLED (July 15, 2026)
The display backplane - the grid of thin-film transistors sitting behind the pixels - is one of the major constraints on what an OLED display can do, and it is also the component that wastes most of the panel's energy, more than the OLED emitters themselves. This is the opening article of a new seven-part practical guide to the backplane technologies of today and of the future.

Part 1 defines what a backplane actually is, explains why the transistor's job in an emissive OLED is fundamentally harder than in an LCD, and lays out the road ahead: a-Si, LTPS, oxide TFT (IGZO), LTPO, high-mobility oxide, and finally organic TFTs and silicon CMOS microdisplay backplanes. It then covers PMOLED - the backplane-free OLED - how passive-matrix addressing works, what it costs in resolution and brightness, and where that market stands today.
A Walk Down Memory Lane - Q3 2026: OLED History from 20, 10, and 5 Years Ago (July 1, 2026)
Our quarterly history feature returns, revisiting the OLED industry as it stood 20, 10 and 5 years ago. In the summer of 2006 the industry was still tiny, built mostly around PMOLED displays for mobile sub-displays and music players, while AMOLED makers wrestled with yields - DisplaySearch put OLED at just 3.5% of the small and medium display market at the end of Q2 2006.
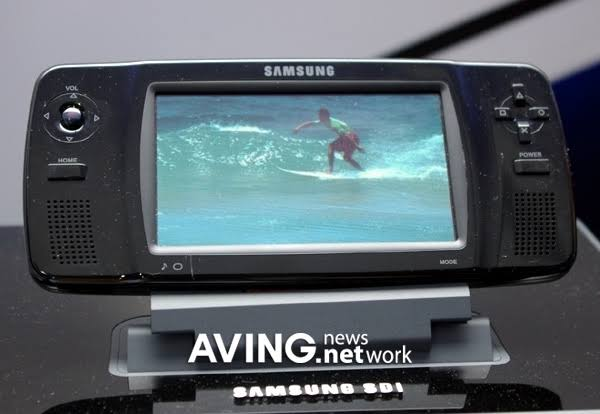
Two names that loom large today were already making their moves: LG Electronics was in talks to sell its PMOLED business to LG.Philips LCD, and Samsung SDI showed a 4.3-inch WQVGA AMOLED at IMID 2006 using its Super Grain Silicon backplane. The two even sparred in public over which had the thinner panel. The article carries the story forward through 2016 and 2021, and revisits the gadgets of the era - Sony's organic-EL Walkman players, the mirror-finish Sony Ericsson Z610, and the cult Optimus mini three OLED keyboard.
Visionox is one of China's pioneering AMOLED producers, and arguably the industry's most technically ambitious second-tier player. Grown out of an OLED research group established at Tsinghua University in 1996, the company built mainland China's first PMOLED line, its first AMOLED pilot line and its first dedicated Gen-5.5 AMOLED mass-production line. It holds roughly 10% of the global smartphone AMOLED market and had shipped more than 240 million OLED panels cumulatively by the end of 2024.

It is also the cautionary tale of the OLED industry: the smallest of the OLED-focused panel makers and the only major producer still loss-making in 2025, with roughly $1.2 billion in accumulated net losses over three and a half years, and a ~$410 million rescue in late 2025 from a Hefei government investment arm that became its largest shareholder and de facto controller. That tension between real technology leadership and a strained balance sheet runs through the whole deep dive - the corporate structure and Tsinghua roots, the fabs and capabilities, ViP and pTSF, the spin-outs, the microLED roadmap, the stock, and above all the $7.6 billion 8.6-Gen bet that will be the first in the world to attempt maskless OLED production at scale.
Bright Side with Brannan | Open-Shell Emitters for OLEDs: A Radical Alternative? (June 8, 2026)
The article that launched Prof. Brannan's column looks at open-shell emitters - radicals, molecules carrying an unpaired electron in the valence shell - and why a family of compounds usually associated with instability and oxidative damage has become one of the more interesting directions in OLED emitter research.
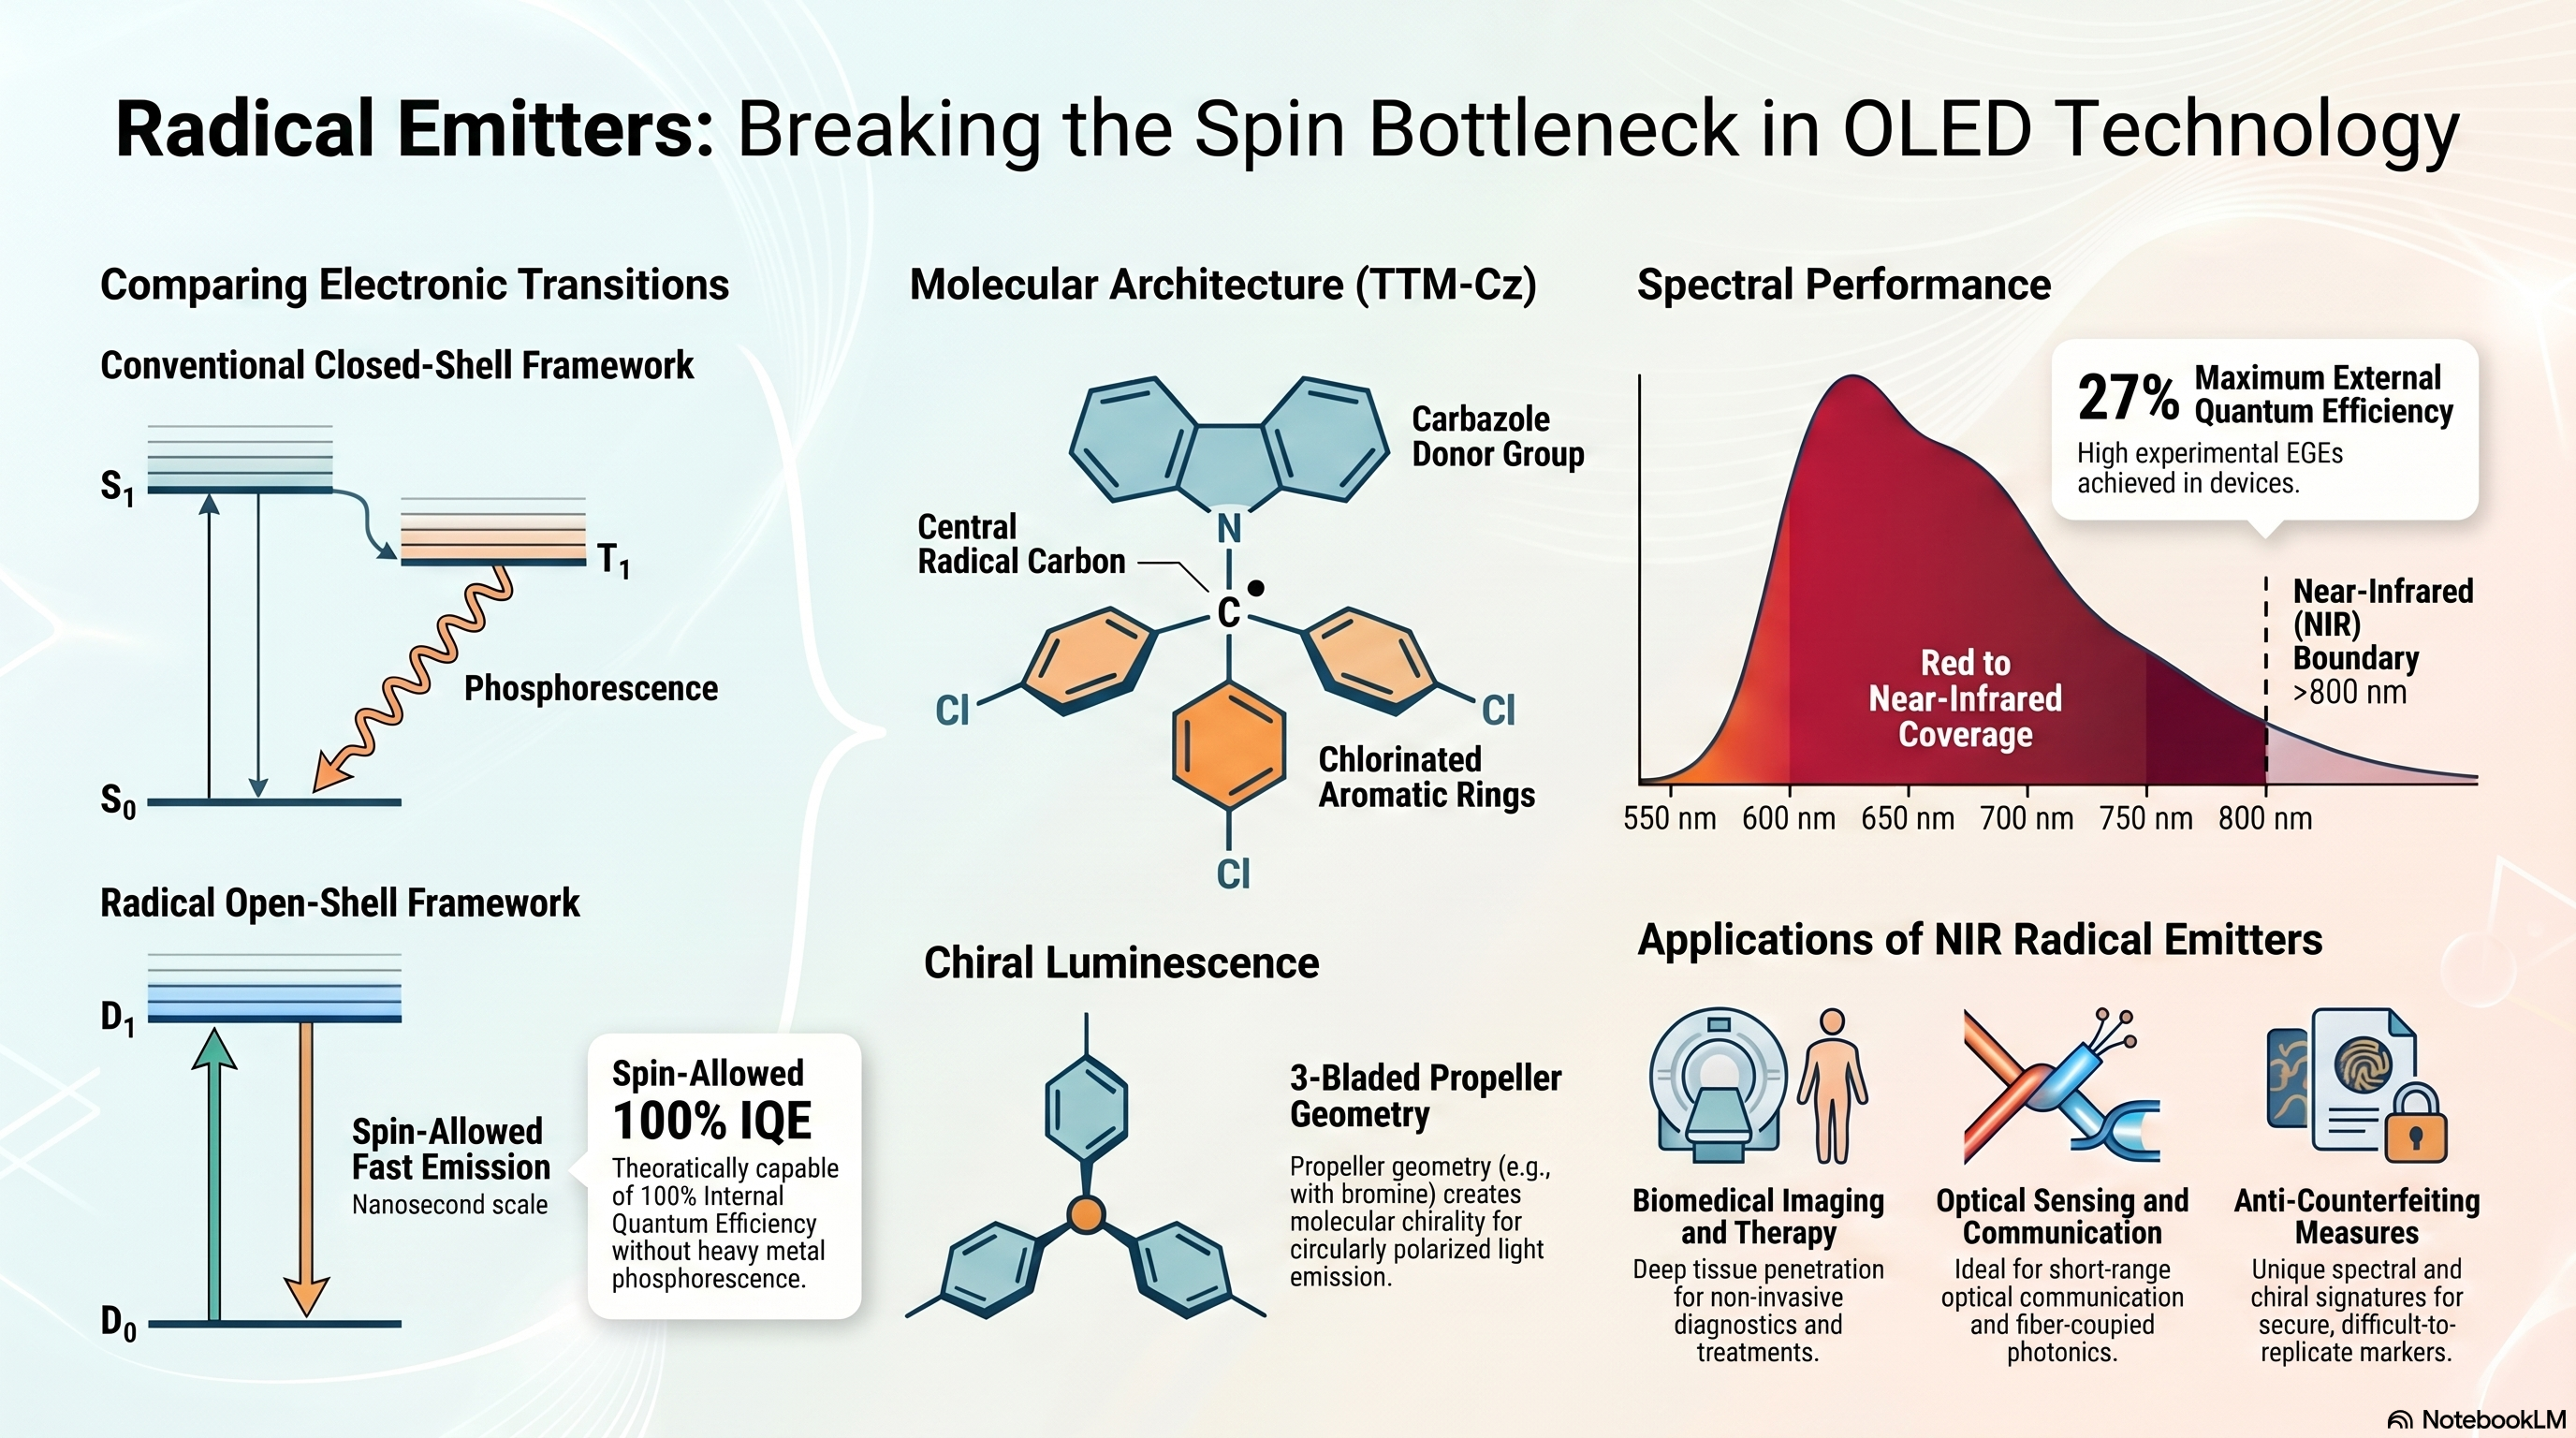
The piece starts from the spin problem at the centre of OLED emitter design: conventional fluorescent emitters are capped at 25% internal quantum efficiency because only singlet excitons emit efficiently, while phosphorescent and TADF emitters harvest triplets at the cost of long excited-state lifetimes and other complications. Radical emitters change the terms of that trade. The article explains how a small family of radicals achieves remarkable stability through steric protection, rigid geometry and electronic delocalisation, what their different spin structure makes possible, and where the honest limitations still lie.
China's 15th five-year plan and the implications for the OLED display industry (June 3, 2026)
When China published its 15th Five-Year Plan (2026-2030) in March 2026, many assumed the display industry had been handed another wave of state-level support. The assumption was understandable, but the text requires a more careful reading - displays, and specifically "New Displays", are not named as a standalone pillar anywhere in the plan.

The article explains what a Chinese five-year plan actually binds and what it merely indicates, then goes through the numbers: annual R&D spending to rise by at least 7%, a "core digital economy" at 12.5% of GDP by 2030, AI-related industries above 10 trillion yuan, and a 2026 GDP growth target of 4.5-5% - the most modest in three decades. From there it works out the implications for Chinese display investment, what it means for the Korean makers, and how the alternative geographies - Japan, India and the United States - are positioning themselves in response.
OLED under macro-pressure: memory prices, geopolitics and LCD challenges (May 20, 2026)
At the end of 2025 the expectation was that 2026 would bring another year of rising AMOLED shipments, even before the two new 8.6-Gen IT OLED lines came online. Instead, macro constraints began to shape demand and the market started to contract. The clearest example is memory: DRAM and NAND prices rising sharply on AI datacenter demand, raising smartphone build costs and pulling shipment estimates down by 10-14% for the year.

The squeeze hits hardest where margins are thinnest, and some brands are switching back to LCD in budget and mid-range smartphones - display technology chosen by system cost rather than by capacity or performance. The report examines the three macro constraints shaping the industry in 2026, why this cycle differs from earlier ones, what the post-COVID IC shortage taught us, which OLED segments are proving most resilient, and the four ways OLED producers are responding.
All of these articles, along with the full premium archive, market reports, guides, OLED Industry AI Agent, video lectures and the OLED Library, are available to OLED-Info Pro subscribers.